FG Unveils 11 Major Economic Reforms, Promises Results
The Federal Government has unveiled a scorecard detailing 11 major economic and financial reforms implemented between May 2023 and December 2025, saying the measures are designed to address longstanding structural weaknesses and lay the foundation for sustainable economic growth.
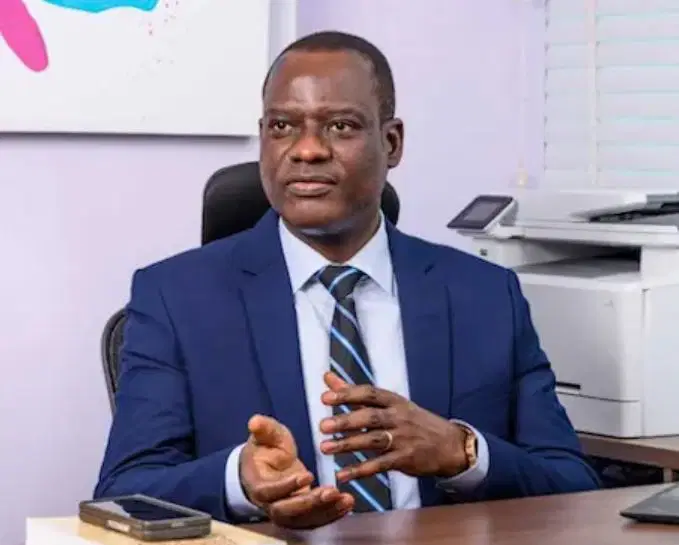
Minister of Finance and Coordinating Minister for the Economy, Taiwo Oyedele, presented the reform scorecard during a media briefing as the administration intensified efforts to explain its economic policies and their impact on Nigerians.
The government said the reforms cover critical areas including fiscal policy, taxation, foreign exchange, education, infrastructure, labour, energy and capital markets.
According to the Federal Government, the objective is to strengthen public finances, improve revenue mobilisation, attract investment, support businesses and build greater resilience within the Nigerian economy.
Reform Agenda Covers Major Economic Sectors
Among the measures highlighted by the government are the removal of the petroleum subsidy, changes to foreign exchange management, tax reforms and measures aimed at improving fiscal administration.
The government has also listed reforms affecting the labour market, energy sector, infrastructure development, banking and capital markets.
The reforms represent some of the most significant policy changes introduced since President Bola Tinubu assumed office in May 2023.
The administration has repeatedly argued that Nigeria’s previous economic structure was unsustainable, particularly because of pressure on public finances, foreign exchange shortages, low government revenue and rising debt-service obligations.
The reform programme was therefore designed to address these structural issues while creating conditions for greater private-sector participation.
Fuel Subsidy Removal Remains Central
One of the most consequential reforms was the removal of the petrol subsidy shortly after President Tinubu took office.
The policy immediately changed the structure of petrol pricing and significantly increased the cost of transportation and other goods and services.
The Federal Government has maintained that subsidy removal created additional fiscal space and reduced the financial burden previously associated with subsidising petrol consumption.
Oyedele recently disclosed that N15.8 trillion was paid into the Federation Account between June 2023 and December 2025 as proceeds associated with petrol subsidy removal. The Federal Government received N5.4 trillion, while states and local governments received N10.4 trillion during the period, according to the minister.
However, the policy has also remained controversial because of its impact on household purchasing power and living costs.
Foreign Exchange Reforms
The government’s foreign exchange reforms are another major component of the economic restructuring.
The administration moved towards a more unified foreign exchange market in an attempt to reduce distortions and improve transparency in the determination of the naira’s value.
The reforms were introduced amid severe foreign exchange shortages and a wide gap between official and parallel-market exchange rates.
The government argues that a more market-driven foreign exchange system can improve transparency, attract investment and reduce opportunities for arbitrage.
For businesses, however, exchange-rate volatility remains an important challenge, particularly for companies dependent on imported raw materials and equipment.
Tax Reforms
Tax administration has also undergone major changes.
The government has introduced new tax legislation as part of efforts to simplify Nigeria’s tax system, improve compliance and expand revenue mobilisation.
The Federal Government says a stronger tax system is necessary to reduce excessive dependence on borrowing and volatile revenue sources.
For businesses and individuals, however, the implementation of tax reforms will remain an important issue, particularly regarding compliance costs and the effect of new requirements on small and medium-sized enterprises.
The government has maintained that improved revenue collection should ultimately provide greater resources for public services and infrastructure.
Banking and Capital Market Reforms
The reform programme also includes measures affecting Nigeria’s financial sector.
The government has highlighted bank recapitalisation and capital-market reforms as important steps towards strengthening financial institutions and increasing their capacity to support economic activity.
A stronger banking sector could improve the ability of financial institutions to provide credit to businesses and support investment.
Capital-market reforms are similarly intended to improve investor confidence and create additional opportunities for companies and governments to raise long-term financing.
Energy and Infrastructure
Energy-sector reforms form another major part of the government’s economic agenda.
The administration has continued to pursue reforms intended to improve electricity supply, encourage investment and expand domestic utilisation of Nigeria’s energy resources.
The Electricity Act has also created a framework allowing states to participate more directly in electricity generation, transmission and distribution within their territories.
Meanwhile, infrastructure development is being supported through government projects and public-private partnerships.
The government argues that better infrastructure is essential for reducing business costs, improving productivity and attracting investment.
Labour and Social Measures
The reform agenda also includes measures relating to workers and household welfare.
The government has highlighted the National Minimum Wage Amendment Act as part of its labour and welfare response.
The new wage framework was introduced against the background of increased living costs following major economic changes, particularly fuel subsidy removal and exchange-rate reforms.
The challenge for policymakers remains ensuring that wage increases and other interventions provide meaningful relief without creating additional pressures on businesses and public finances.
Government Promises Transparency
As it unveiled the scorecard, the Federal Government stressed that economic reform should not be viewed as a one-time exercise.
The Ministry of Finance said the reform process requires difficult decisions, sustained commitment and transparent reporting.
“Transparency and accountability remain central to the reform process,” the government said, adding that Nigerians deserve to understand what is being done, why it is being done, the results being achieved and the challenges that remain.
The ministry plans to spend 11 days examining the individual reforms, including their objectives, implementation progress and impact on the economy and citizens.
Government Says More Work Remains
Despite highlighting progress, the Federal Government acknowledged that significant work remains before the reforms can deliver all their intended outcomes.
This acknowledgement is important because some of the policies have produced substantial short-term economic pressures.
Inflation, exchange-rate volatility, high living costs and difficulties faced by businesses remain major concerns for households and investors.
The government’s argument is that the reforms are intended to correct underlying weaknesses and that their full benefits will take time to emerge.
What the Reforms Mean for Nigerians
For ordinary Nigerians, the success of the reform programme will ultimately be judged by whether economic improvements translate into better living standards.
Improved government revenue, for example, will have greater significance if it results in better roads, electricity, healthcare, education and other public services.
Similarly, foreign exchange reforms will be more meaningful to businesses if they eventually contribute to greater currency stability and predictable access to foreign exchange.
Tax reforms will also need to balance increased government revenue with an environment in which businesses can continue to operate, invest and create employment.
The Road Ahead
The Federal Government’s release of the 11-point scorecard marks an attempt to provide a more structured assessment of the economic policies introduced since 2023.
The reforms represent a broad restructuring of fiscal policy, taxation, foreign exchange, energy, labour, infrastructure and financial markets.
While the administration says the measures are laying the foundation for sustainable prosperity, the ultimate test will be their implementation and the extent to which Nigerians experience tangible improvements.
For now, the government is promising continued reporting, greater transparency and further work on the reforms.
As the 11-day review progresses, Nigerians are expected to receive more detailed information about the individual policies, the results recorded so far and the challenges that remain.
The central question will be whether the reforms can move beyond policy announcements and translate into stronger economic growth, greater investment, improved public finances and better living conditions for citizens.
This report is based on the Federal Government’s Reform Scorecard presentation and recent reports on the economic reform programme. Government claims about the impact of the reforms are presented as official positions and should be assessed alongside independent economic data as further information becomes available.
